


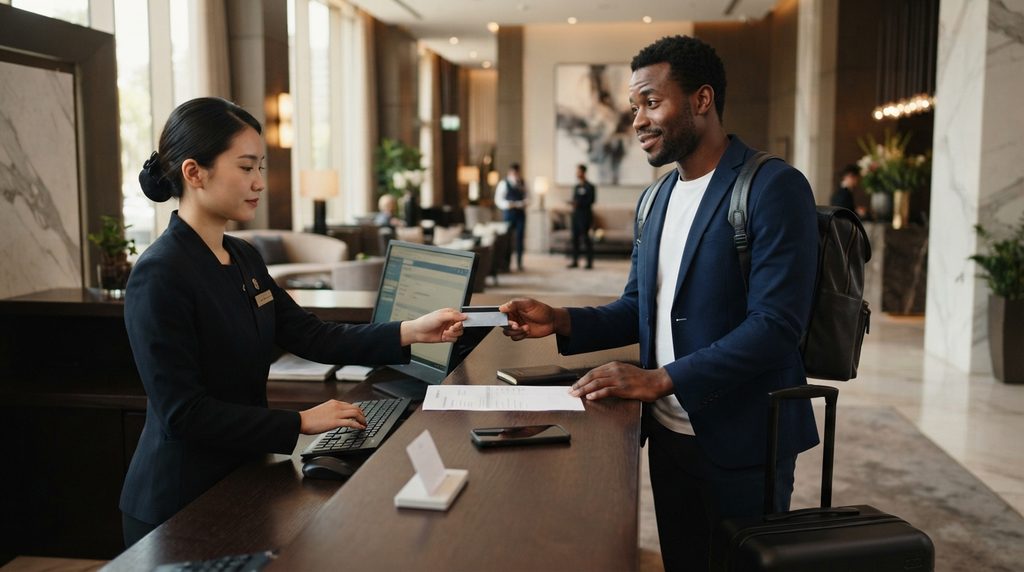
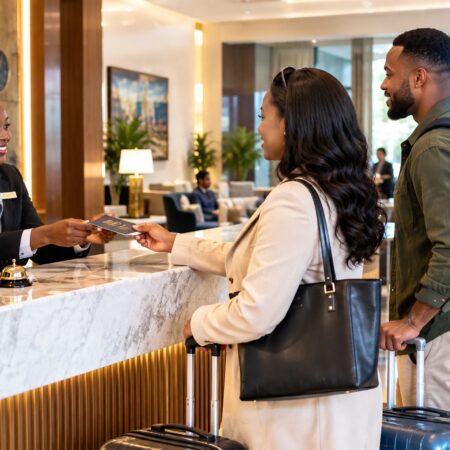
You booked and paid for your hotel weeks in advance, confident that check-in would be a simple matter of collecting your key. Then, at the front desk, you are asked for a credit card despite having already settled the bill in full. For many travellers, this moment triggers confusion, frustration, and sometimes suspicion that something has gone wrong with the booking. In reality, this practice is standard across much of the hotel industry, and understanding why it happens can turn a moment of irritation into a simple, expected part of check-in.
It Is Not About the Room Rate
The first thing to understand is that the credit card requested at check-in is rarely about the cost of the room itself. If a reservation has already been paid in full — whether through a booking platform, a travel agency, or directly with the hotel — that portion of the transaction is genuinely complete. What the hotel is requesting instead is a form of security against costs that have not yet been incurred, and may never be incurred at all.
This distinction is important. Many guests assume that being asked for a card at check-in means their original payment did not go through, or that the hotel is attempting to charge them twice. In the vast majority of cases, neither is true. The card is simply being placed on file as a guarantee, not processed as an additional payment.
What the Card Is Actually Securing
Hotels operate in an environment where guests have access to a wide range of services and amenities that are not included in the base room rate. A credit card on file protects the property against costs that may arise during the stay, including:
Incidental charges. Minibar usage, room service, spa treatments, or laundry services are often billed directly to the room and settled at checkout. Without a card on file, hotels would have no reliable way to collect these charges from a guest who has already left.
Property damage. While the vast majority of guests cause no damage whatsoever, hotels must account for the possibility of damaged furniture, stained linens, or broken fixtures. A card on file provides a mechanism to cover repair or replacement costs if necessary.
Missing items. Items such as remote controls, towels, or in-room amenities occasionally go missing. A credit card guarantee allows hotels to address this without needing to pursue the guest after departure.
No-show or early departure penalties. In some cases, particularly with certain rate types, penalties may apply if a guest fails to arrive or leaves earlier than the reserved dates. A card on file ensures these terms, agreed to at booking, can be enforced fairly.
Smoking or policy violations. Many hotels enforce cleaning fees for violations of no-smoking policies or other property rules, and the card on file serves as the mechanism for collecting these fees if they apply.
Authorization Holds vs. Actual Charges
A key concept travellers should understand is the difference between an authorization hold and an actual charge. When a hotel requests a card at check-in, it typically places a temporary hold, sometimes called a pre-authorization for an estimated amount rather than charging that amount outright.
This hold temporarily reduces the available balance or credit limit on the card but does not represent money actually taken from the account. If no incidental charges occur during the stay, the hold is released, usually within a few days to two weeks after checkout, depending on the card issuer’s own processing timelines. This is an important distinction, because travellers using debit cards in particular should be aware that a hold can temporarily limit access to funds, even though no purchase has technically been made.
Why Debit Cards Are Often Treated Differently
Many hotels prefer credit cards over debit cards for this exact reason. A hold placed on a credit card affects available credit, which is generally a less immediate concern for most travellers. A hold placed on a debit card, however, affects actual available cash, which can create real inconvenience if a traveller is relying on that account for other expenses during the trip.
Some hotels accept debit cards for this purpose but may require a larger hold amount, additional identification, or proof of a return ticket, particularly for international travellers. Understanding a hotel’s specific policy in advance can help prevent unexpected cash-flow issues during a trip.
How to Prepare and Avoid Surprises
While this practice is standard, a few simple steps can help travellers avoid confusion or inconvenience at check-in:
- Review the hotel’s policy before arrival. Most hotels list their credit card and deposit requirements in the booking confirmation or on their website, often under a section covering check-in requirements or incidental holds.
- Bring a credit card when possible, even if the stay itself has been prepaid, since this is the preferred and often required method for securing incidentals.
- Ask about the exact hold amount at check-in, as this varies by hotel and can range from a fixed nightly estimate to a set flat amount for the entire stay.
- Monitor the account after checkout to confirm that any hold has been released within the expected timeframe, and contact the hotel directly if it has not.
- Travel with a backup card where possible, particularly for international trips, in case a hold temporarily limits available funds on the primary card.
Conclusion
Being asked for a credit card after a stay has already been paid for can feel unexpected, but it reflects a standard and well-established hotel industry practice rather than any error or double billing. The card on file exists to protect against incidental costs that may or may not occur, not to reprocess a payment that has already been made.
Travellers who understand this distinction and who prepare accordingly by bringing the right card and reviewing hotel policies in advance can approach check-in with confidence rather than confusion, knowing exactly what the request means and why it exists.
Fill this FORM to book your hotel today.

Other Articles
How to Book Flights for a Wedding Party Without the Chaos
What Changes When Your Course Requires a Mandatory Placement Year
No Comment! Be the first one.