


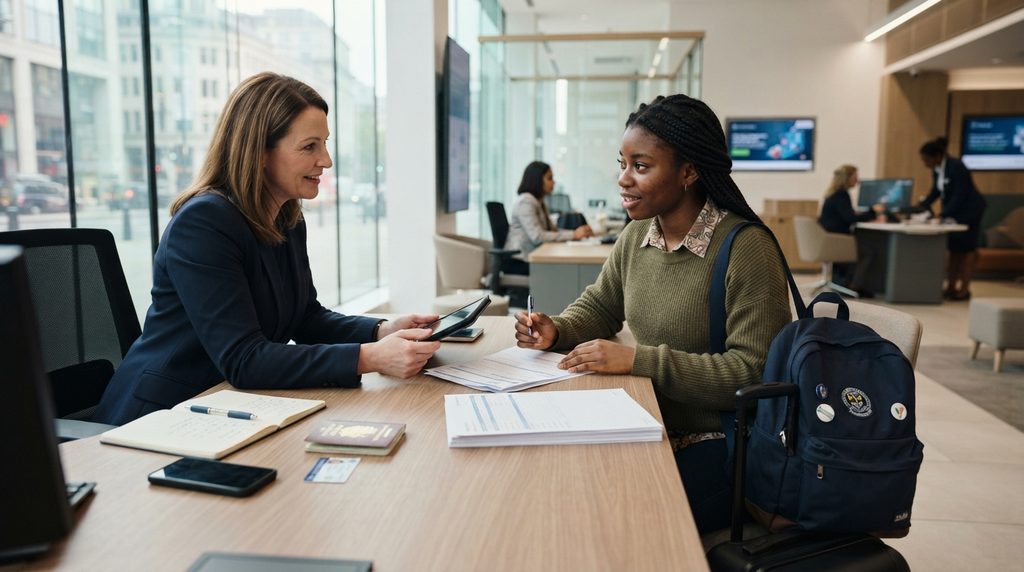
Somewhere between securing a visa, booking flights, and arranging accommodation, one decision often gets pushed to the bottom of the list: opening a bank account. Yet this single choice quietly affects almost every financial interaction a new international student will have, from paying rent and receiving part-time wages to avoiding costly currency conversion fees on everyday purchases. Choosing the wrong account, or delaying the decision entirely, can lead to unnecessary charges and frustrating limitations during the very weeks when settling matters most. Understanding what to look for before arrival can make this one decision remarkably simple.
Why This Decision Deserves Early Attention
Many new international students assume that any bank account will do, planning to sort out the details once they arrive. In practice, banking systems, requirements, and available account types vary significantly by country, and some steps — such as document verification or proof of address — can take days or even weeks to complete. Starting this process with awareness, even before departure, prevents the common scenario of relying entirely on cash or a foreign card with high international fees during the critical first weeks of settling in.
Understand the Documentation You Will Likely Need
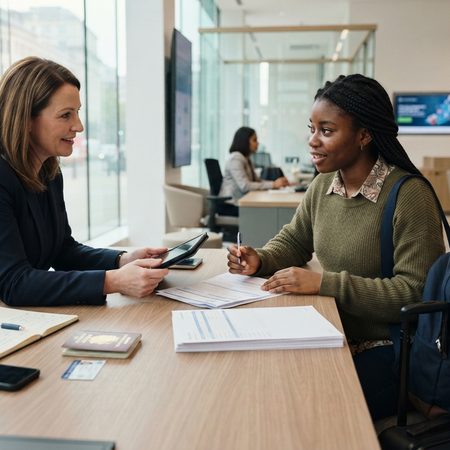
Most banks require a consistent set of documents to open an account for a new international student, though exact requirements vary by country and institution. Commonly requested items include:
- A valid passport and student visa
- Proof of enrolment or an admission letter from the institution
- Proof of address, which may initially be a temporary accommodation letter before a permanent address is secured
- In some cases, an initial minimum deposit to activate the account
Because proof of address can be difficult to provide immediately upon arrival, many banks that specifically cater to international students offer flexible verification processes, sometimes allowing a university-provided address or temporary housing confirmation to suffice initially. Researching which banks offer this flexibility before arrival can prevent unnecessary delays.
Look for Student-Specific Account Options
Many banks offer accounts specifically designed for students, often with reduced or waived fees, no minimum balance requirements, and simplified eligibility criteria for those without an existing local credit history. These accounts are typically a stronger starting point than standard personal accounts, which may carry monthly maintenance fees or balance requirements that are impractical for a student managing a tight budget in a new country.
It is worth directly asking whether a bank offers an international or student-specific account, as these options are not always the default choice presented to new customers and may need to be requested explicitly.
Compare Fees Carefully, Not Just Interest Rates
New international students often focus on interest rates when comparing accounts, but for most students, fees matter far more than interest earned, particularly in the early months. Key fees to investigate include:
Monthly maintenance fees. Some accounts waive these entirely for students, while others require a minimum balance to avoid a monthly charge.
ATM withdrawal fees, particularly for withdrawals outside the bank’s own network, which can add up quickly for students who have not yet identified convenient in-network locations.
International transaction fees, relevant for students who continue to receive support from family abroad or who travel internationally during their studies.
Currency conversion fees, which apply when receiving funds from or sending funds to accounts in a different currency, a common need for international students in the first year.
Comparing these fees across two or three banks before committing can prevent avoidable costs that accumulate steadily over an academic year.
Consider Access to Digital and Mobile Banking
For most students, day-to-day banking now happens primarily through mobile apps rather than in-person branch visits. A bank with a reliable, well-reviewed mobile app can make a significant difference in daily convenience, particularly for tasks like transferring money to roommates for shared expenses, tracking spending, or receiving instant notifications for transactions.
Students should also confirm whether the bank offers straightforward international money transfer options within its app, as this becomes particularly relevant when receiving financial support from family or managing funds across two countries.
Evaluate Branch and ATM Accessibility Near Campus
While digital banking covers most daily needs, having a physical branch or ATM network conveniently located near campus or student housing still matters, particularly for tasks such as depositing cash, resolving account issues in person, or obtaining official documents like bank statements, which are sometimes required for visa renewals or other administrative processes.
Before choosing a bank, it is worth checking whether it has a visible presence near the university or within the areas where students most commonly live, rather than assuming convenience will work itself out later.
Ask About Building Local Credit History
For students planning to stay in the country for an extended period, or those who may eventually seek local employment, housing, or financing, building a local credit history can be valuable. Some banks offer student accounts paired with entry-level credit products or clear guidance on how responsible account use contributes to establishing credit within the local system.
Even for students who do not anticipate needing credit immediately, understanding this early can prevent complications later, particularly for those who remain in the country beyond their initial studies.
Practical Steps Before and After Arrival
To simplify the account-opening process, new international students should consider the following approach:
- Research bank options before departure, focusing on institutions known for supporting international or new-to-country students.
- Prepare documentation in advance, including digital and physical copies of passports, visas, and admission letters.
- Ask specifically about student account options, as these are not always the default offering.
- Compare fee structures across at least two or three banks, prioritising low fees over marginal interest rate differences.
- Confirm mobile banking capabilities, particularly for international transfers.
- Visit a branch near campus during the first week, once temporary or permanent accommodation is confirmed, to complete account setup promptly.
Conclusion
Choosing a bank account may seem like a minor administrative task compared to the excitement of starting a new academic journey abroad, but it quietly shapes daily financial life for the entire duration of a student’s studies. Taking the time to research options, understand fees, and prepare documentation in advance transforms this often-overlooked decision into one less thing to worry about, leaving more energy for what truly matters: settling in and making the most of the experience ahead.
Fill this FORM to start your study abroad journey.

Other Articles
What to Confirm Before Booking a Hotel Near an Airport
How to Book Flights for a Wedding Party Without the Chaos
No Comment! Be the first one.